Industries · Consumer
Multiple outlets often mean multiple entities, inter-company charges and consolidated reporting. We keep each entity clean, the charges consistent and the group picture honest.
Sounds familiar
“Every outlet keeps its books a different way.”
One chart of accounts and one monthly rhythm across every entity. Comparing outlets becomes possible, then automatic.
“Opening outlet five nearly broke our old accountant.”
When the method is standard, a new outlet adds days of work, not months. Growth should not be rationed by bookkeeping.
“The group picture takes three weeks to assemble.”
Inter-company balances tracked all year make consolidation mechanical. The group P&L arrives with the outlet ones.
Chains drift into trouble when each entity keeps books its own way and nobody can compare outlets. We put every entity on the same chart of accounts and the same monthly rhythm, set inter-company charges on a documented basis, and produce a consolidation the banks and your directors can rely on. Adding outlet number nine then costs days, not months.
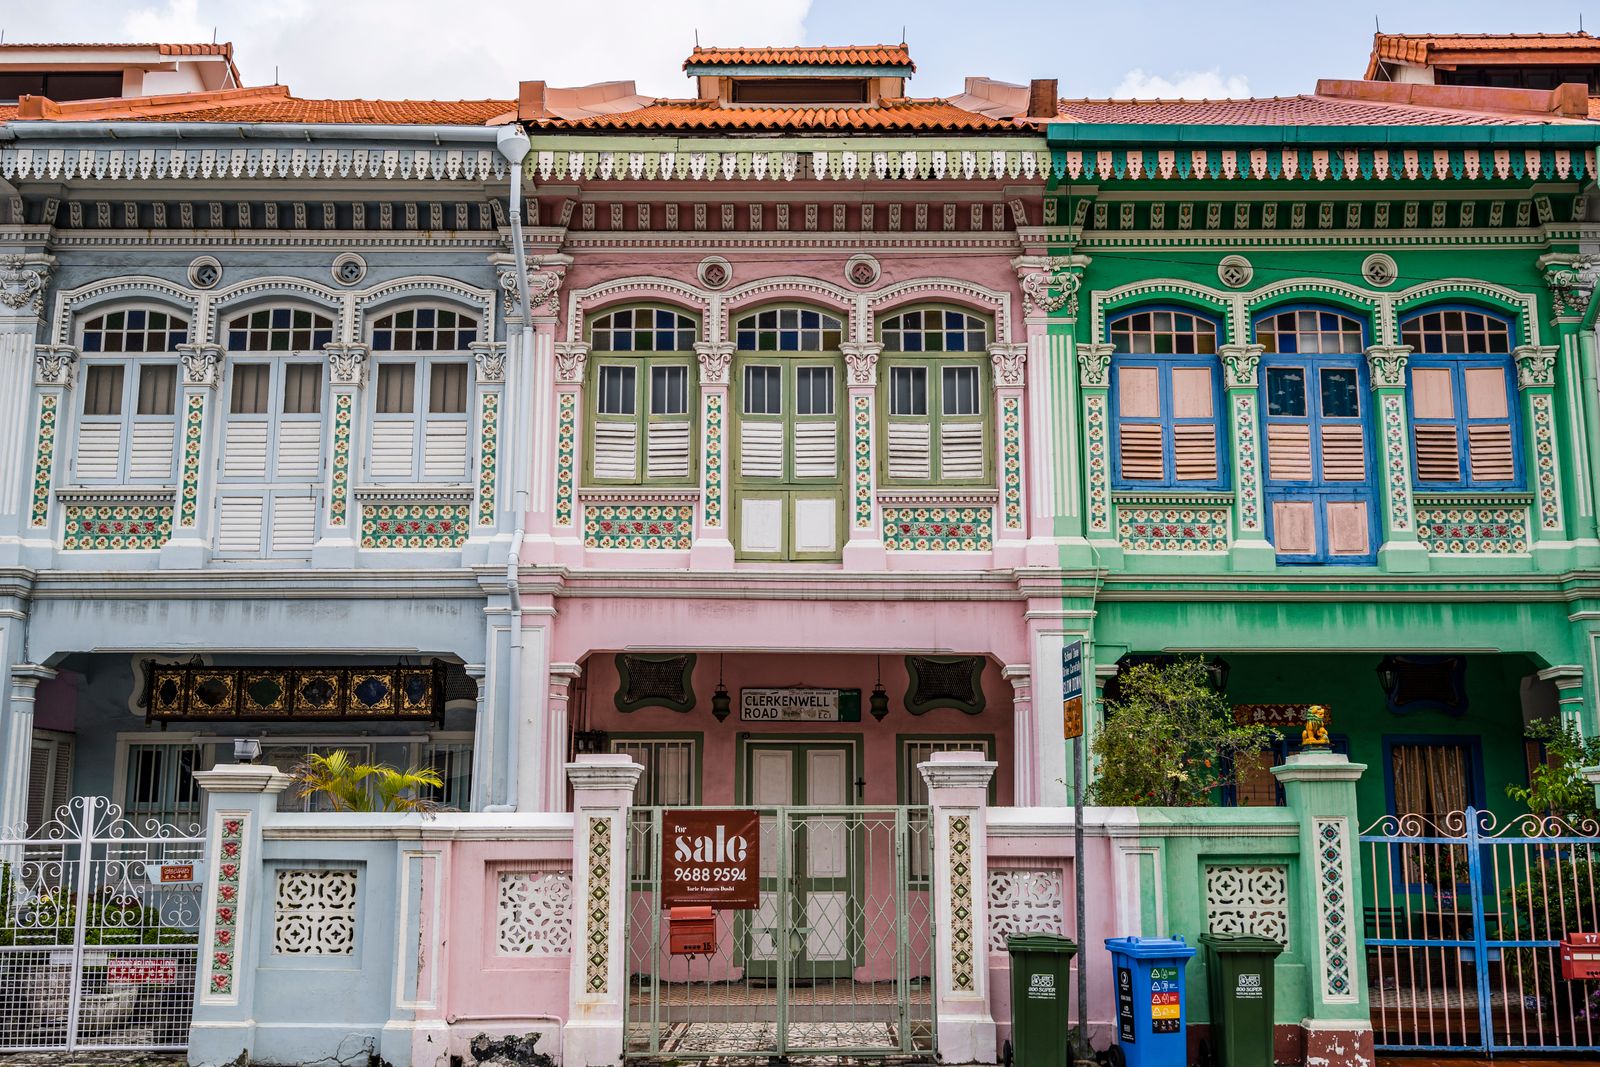
Chains thrive on consistency and so do their books: standard charts, documented inter-company charges and a consolidation that closes with the month.
Standard chart groupwideInter-company documentedConsolidated monthly
Not sure where to start?
Tell us where your books stand. An expert accountant replies within one working day.
Yes. Multi-entity groups are routine for us. Each company gets clean books and the group gets one consolidated view.
Per entity with scoped volume, agreed in advance. Groups typically save because the entities share one team and one method.
Yes. We set the inter-company basis with you once, document it, and apply it every month so both management truth and tax positions hold.
Not necessarily. Small company audit exemption applies per entity and group thresholds matter. We assess your structure and tell you exactly which entities need what.
Yes, we consolidate Singapore groups with regional subsidiaries and handle the currency translation involved.
Did not find your question? Ask us on WhatsApp and an expert accountant replies within one working day.
Tell us the structure and we will map the cleanest way to run it.
Accounting, corporate secretarial, payroll and advisory for Singapore SMEs since 2012.
Get in touch
Ian & Son refers to the Ian & Son network and/or one or more of its member firms, each of which is a separate legal entity. Contact us to learn more.