Industries · Commercial & Industrial
Raw materials, work in progress, wastage and machine costs decide whether a factory makes money. We build a costing view that matches how your floor actually runs.
Sounds familiar
“I price from gut feel because costing is a mess.”
Material, labour and overhead per unit, allocated on drivers that match your floor. Quotes get a foundation.
“Wastage is a feeling, not a number.”
Yield tracked per run or period makes wastage a managed number with a trend, not a shrug.
“New machines, but the claims were never made.”
Plant and machinery attract capital allowances with elections worth planning. We claim what the investment deserves.
Factories fail on paper when overheads get spread evenly across products that use machines very differently. We allocate costs on drivers that reflect reality, track yield so wastage is a number rather than a feeling, and claim capital allowances on plant the way IRAS intends. The month-end report then tells you which products deserve the machine time.
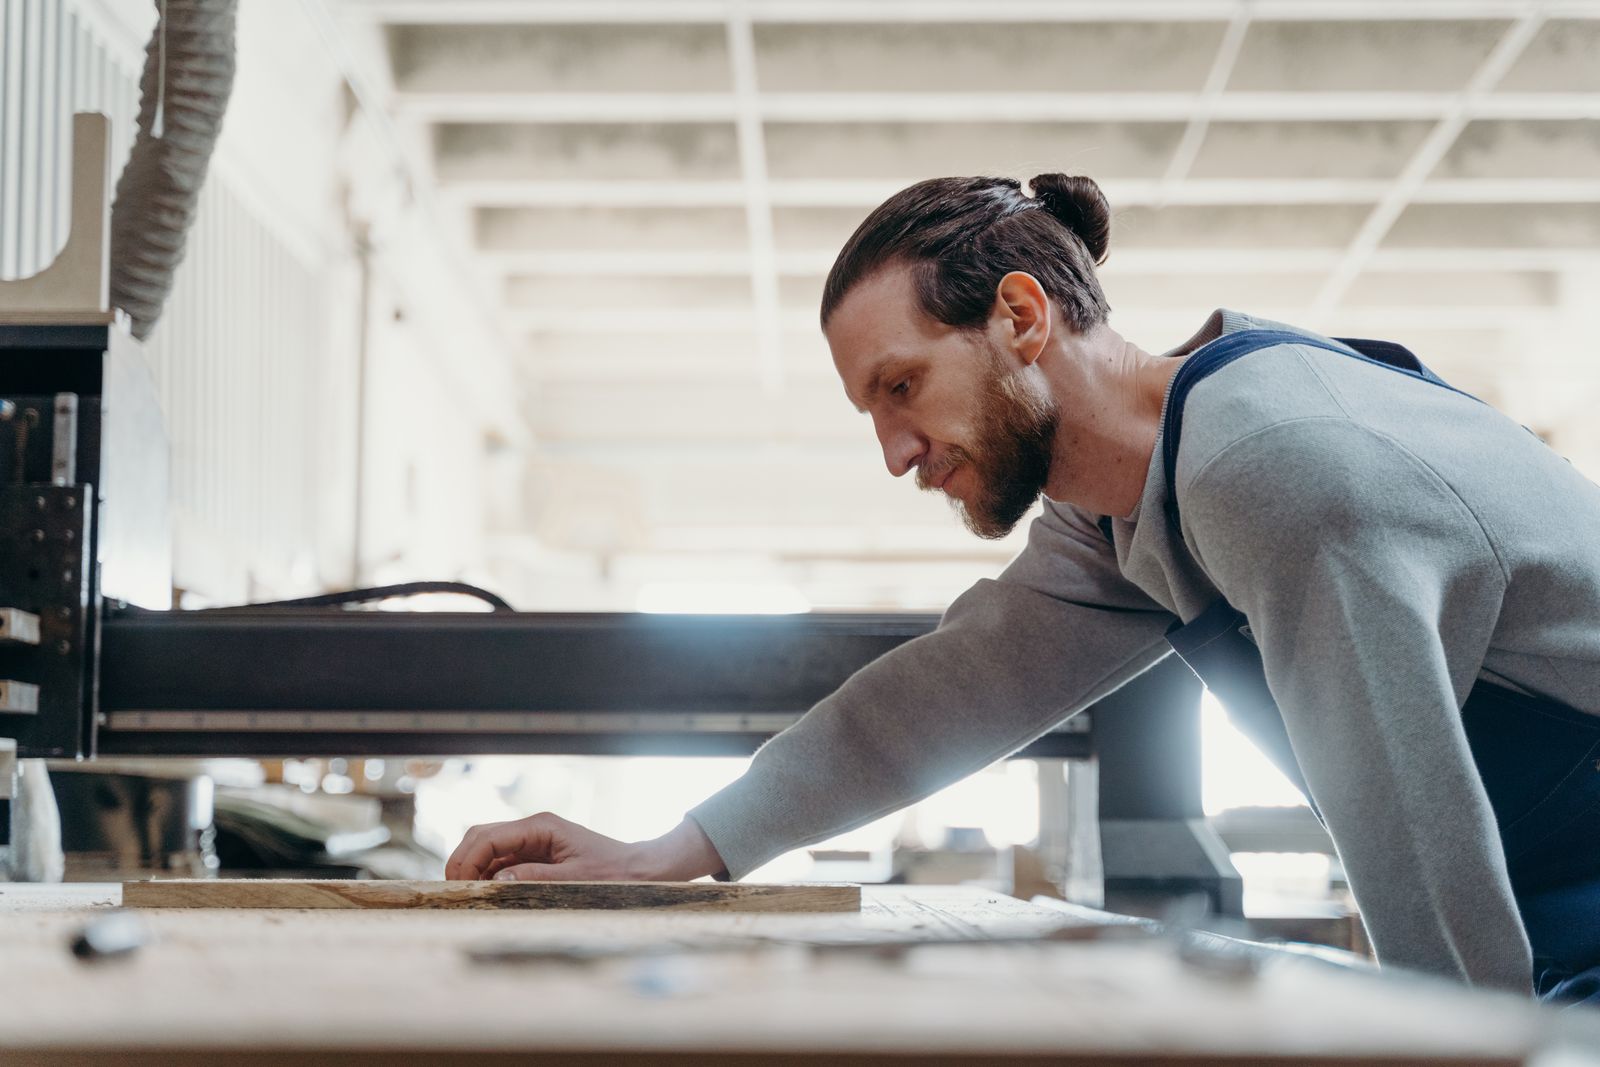
A factory is a costing machine that happens to make products. When the costing is right, pricing, purchasing and expansion all get easier.
Unit cost knownYield trackedAllowances claimed
Not sure where to start?
Tell us where your books stand. An expert accountant replies within one working day.
Yes. Material, labour and allocated overhead per product line, with margins ranked so pricing decisions have a base.
Work in progress is valued consistently each month so profit is not distorted by where the production cycle happened to pause.
Plant and machinery attract capital allowances including enhanced options in some years. We claim the most favourable treatment available.
Yes. Input against output per run or period, with variances flagged for the operations team.
Where your system exports data, yes. Otherwise we design a light monthly capture that does not burden the floor.
Did not find your question? Ask us on WhatsApp and an expert accountant replies within one working day.
Accounting, corporate secretarial, payroll and advisory for Singapore SMEs since 2012.
Get in touch
Ian & Son refers to the Ian & Son network and/or one or more of its member firms, each of which is a separate legal entity. Contact us to learn more.